
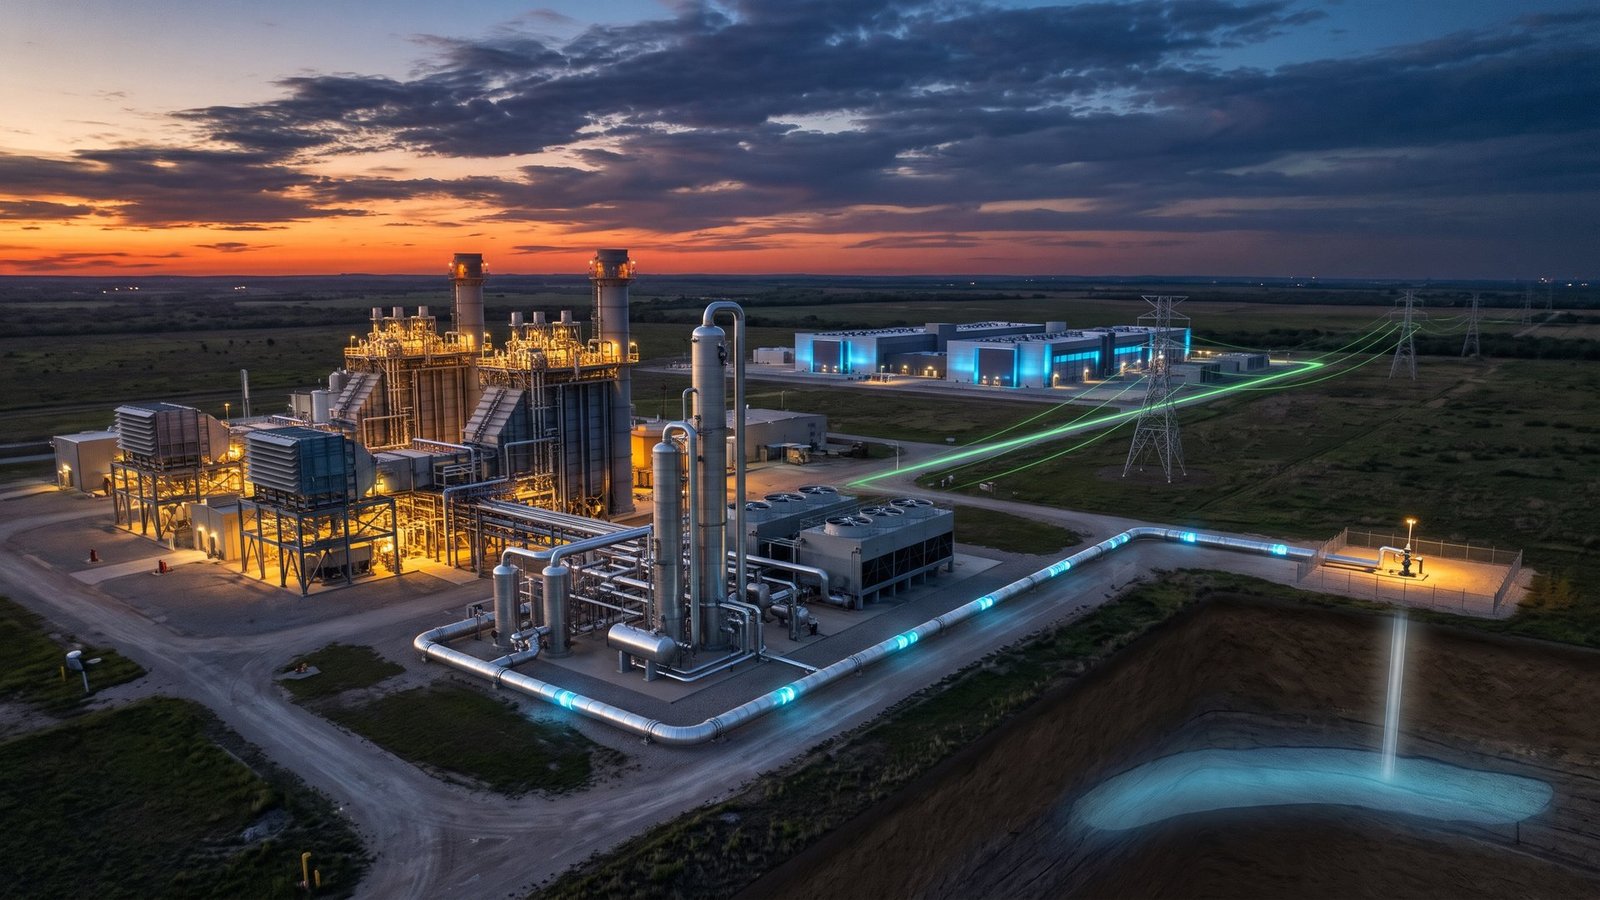
Why carbon capture is back in the AI conversation
AI is changing the relationship between computing and energy. For decades, data centers were sited for fiber, land, taxes, water and access to utility power, and developers could assume the utility would eventually deliver. That's no longer a safe bet. AI campuses now need hundreds of megawatts, and some approach a gigawatt. Power has gone from one factor in site selection to the deciding one. That's the AI Power Wall.
AI data centers need firm, around-the-clock electricity. A multi-billion-dollar GPU cluster can't shut down whenever the sun sets or the wind drops. Wind and solar will supply a lot of AI's energy, and batteries help cover short gaps. But many developers are turning to natural gas to keep the lights on, because it's available, dispatchable and fast to build compared with nuclear.
That creates an obvious problem: emissions. If AI's growth runs partly on gas, can carbon capture and storage (CCS) keep the climate cost in check? A 2026 study from Rice University, and a wave of real projects since we first published this article, suggest the answer could be yes, in the right places.
How carbon capture and storage works
CCS does three things:
- 1.Capture. At a gas power plant, equipment separates carbon dioxide from the exhaust, typically capturing 90% or more of it. This is called post-combustion capture.
- 2.Transport. The CO2 is compressed and moved by pipeline to a storage site.
- 3.Storage. It's injected more than a mile underground into deep rock formations, usually saline aquifers (porous rock filled with salty water), where it's trapped permanently beneath layers of impermeable rock.
These injection wells are regulated by the EPA as Class VI wells, with strict rules for site characterization, monitoring and long-term care. The U.S. also offers a federal tax credit, known as 45Q, for each ton of CO2 permanently stored, which is a key driver of project economics.
What the Rice study found
The study, by Rice University researchers Hon Chung Lau and Steve C. Tsai, was published in 2026 in the American Chemical Society journal Energy & Fuels. It puts hard numbers on the challenge.
It projects U.S. data center power capacity growing from 40 GW in 2025 to 169 GW in 2030, a 4.2-fold increase. If fossil fuels supply a meaningful share of that power, related CO2 emissions could rise from about 90 million metric tons a year to more than 404 million, a 4.5-fold increase. For context, 404 million tons is more than the annual emissions of most U.S. states.
The good news is geology. Saline aquifers make up more than 95% of total U.S. CO2 storage capacity. The researchers found 34 states have enough in-state capacity to store more than 100 years of projected injection beyond 2030. They estimate these formations could have stored about 66% of data-center-related emissions in 2025, rising to roughly 74% by 2030.
The study also points to where gas-plus-CCS could work best. Fast-growing data center markets include Texas, Virginia, Pennsylvania, Ohio, Arizona, Colorado, Utah and Illinois. Texas, Colorado, Louisiana, Mississippi and Pennsylvania stand out for having data center emissions clusters close to both natural gas supply and saline storage.
U.S. Data Center CO2 Emissions, and How Much Could Be Stored
From study to steel: real projects
CCS for data centers is moving from theory to signed deals.
The most important example is Google's Broadwing Energy Center in Decatur, Illinois. Developed by Low Carbon Infrastructure, an I Squared Capital company, on an ADM site, it's a 400 MW gas-fired plant designed to capture and permanently store more than 90% of its CO2. The CO2 will be injected into ADM's Class VI wells in the Mt. Simon sandstone, more than a mile underground. Google signed a first-of-its-kind agreement to buy most of the plant's power. Power is targeted by the end of 2029, with carbon capture running in early 2030.
In December 2025, NextEra and ExxonMobil announced plans for a roughly 1.2 GW gas plant with over 90% carbon capture near Exxon's CO2 pipeline network on the Gulf Coast. They've secured about 2,500 acres and are marketing the site to hyperscalers. As of early 2026, no customer had signed. And in Wyoming, Crusoe and Tallgrass are developing a 1.8 GW AI campus powered by natural gas next to a CO2 sequestration hub, positioning it for capture later.
Law firm Bracewell summed up the trend as the "return of natural gas paired with carbon capture": hyperscalers want reliability, and CCS is how some of them square that with climate goals.
Gas-Plus-Carbon-Capture Projects Aimed at Data Centers
| Project | Partners | Size | Capture and storage | Target |
|---|---|---|---|---|
| Broadwing Energy Center, Decatur, Illinois | Low Carbon Infrastructure (I Squared), ADM; Google buying most of the output | 400 MW | >90% capture; ADM Class VI wells in Mt. Simon sandstone | Power ~2029; capture early 2030 |
| NextEra–ExxonMobil Gulf Coast project | NextEra Energy, ExxonMobil | ~1.2 GW | >90% capture; Exxon CO2 pipeline network | 2028–29 if a customer signs |
| Crusoe–Tallgrass, Wyoming | Crusoe, Tallgrass | 1.8 GW campus (up to 10 GW) | Gas now, near Tallgrass sequestration hub for future CCS | Phased |
Policy is lining up behind it
Two policy shifts make these projects more viable:
- The 45Q tax credit survived. The 2025 federal budget law kept the credit for permanently stored CO2, a core part of CCS economics.
- Permitting is speeding up. In late 2025 the EPA granted Texas Class VI primacy, meaning the Texas Railroad Commission, not just the EPA, now handles permits. Texas joins states such as North Dakota, Wyoming and Louisiana with their own Class VI authority, which should shorten timelines on the Gulf Coast.
CCS is an infrastructure challenge, not a magic fix
CCS has real technical and economic hurdles, and they shouldn't be glossed over.
- Energy penalty. Capture equipment uses a meaningful share of the plant's own energy, reducing net output and efficiency.
- Cost. Capture units, compression, pipelines and injection wells add significant capital and operating costs. CCS plants also face the same gas turbine supply delays as everyone else.
- Not 100%. Capture rates around 90% still leave some emissions. Methane leaks upstream in the gas supply chain aren't addressed by capture at the plant.
- Location-specific. Theoretical storage capacity doesn't mean a project can be built anywhere. It needs suitable geology, pipelines, permits and community support. Pipelines and injection wells can face the same local opposition as data centers.
- Long-term liability. Who monitors stored CO2 for decades, and who's responsible if something goes wrong, must be clearly defined.
These are serious challenges. But they're infrastructure challenges, not reasons to dismiss the technology. Transmission lines, nuclear plants, renewable farms, gas pipelines and utility-scale batteries all face their own permitting, financing and construction hurdles. The real question is whether CCS delivers enough emissions reduction and reliability to justify its cost where firm power is needed.
A portfolio, not a single answer
The strongest AI power strategies will combine several technologies, each doing what it's best at:
- Wind and solar for large volumes of low-cost energy.
- Battery storage for short-duration flexibility and peak support.
- Gas with CCS for firm, dispatchable capacity during long low-renewable periods or grid stress.
- Geothermal and small modular reactors for clean firm power as they scale up in the late 2020s and 2030s.
There's an important difference between energy and capacity. A solar farm can produce enough megawatt-hours over a year to match a data center's annual use, but that doesn't mean power is there every hour. A hyperscale campus needs both annual energy and dependable capacity during the hardest hours. Batteries cover the short gaps, and firm generation covers the long ones.
Gas plus CCS could create new AI corridors
Traditional data center markets like Northern Virginia, Silicon Valley, Dallas and Phoenix grew around fiber and established utilities. Packing more giant loads into those same markets strains transmission and generation. That's pushing developers toward energy-first siting: building where power can be developed, rather than hauling it into congested hubs.
CCS widens that map. Regions with natural gas, pipelines and deep saline storage, such as the Gulf Coast, the Midwest and parts of the Mountain West, could become new AI infrastructure corridors. A campus built there could even become an energy asset for its region, especially if paired with storage and financed with green bonds that require clear emissions reporting.
Conclusion: pragmatic, not perfect
AI is reviving natural gas, and that's not going away soon. The question is whether that gas can be made cleaner. The Rice University study shows the U.S. has the geology to store most of the CO2 that data center growth could create. Projects like Google's Broadwing plant and the proposed NextEra–ExxonMobil development show companies are willing to build it.
CCS won't be cheap, perfect or right for every location. It should complement renewables, storage, geothermal and nuclear, not replace them. But where firm power is essential and the geology is right, gas with carbon capture could be one of the most practical ways to keep AI growing while keeping emissions in check. The challenge isn't choosing between reliability and climate goals. It's building an integrated energy system that delivers both.
This article is based on Hon Chung Lau and Steve C. Tsai, "The Role of Carbon Capture and Storage in Decarbonizing U.S. Data Centers," Energy & Fuels (American Chemical Society), 2026, DOI: 10.1021/acs.energyfuels.6c01309. Updated November 2026 with project and policy developments from POWER Magazine, Bracewell, JD Supra and the Global CCS Institute.
Chris Kalowes
Founder, WattThe?!
Energy intelligence. Simplified.